Most Families Buy a Home. Few Plan What the Home Becomes.
For most families, the first home is the goal. For families who build lasting wealth, it’s the first step. The difference isn’t income. It’s treating each home as the foundation for the next one.
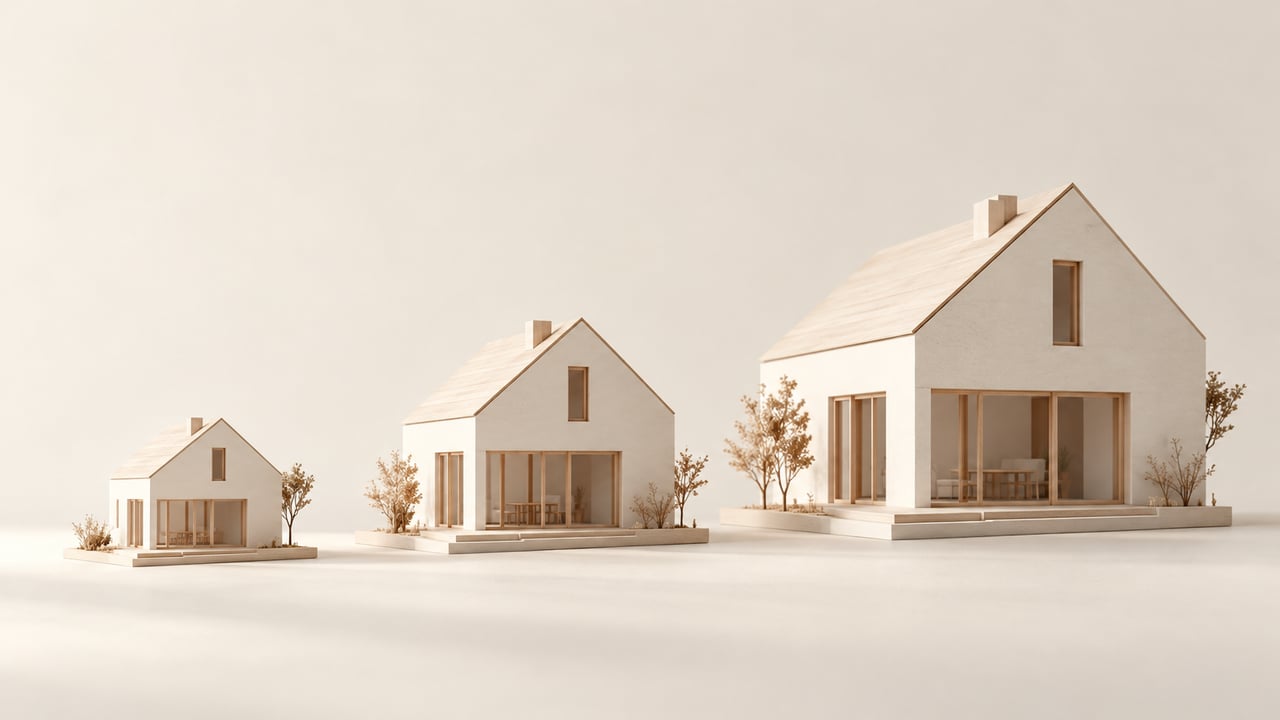
This is the stepping-stone strategy: buy a home you live in, build equity, move up, and keep the earlier home as an asset. Over 15 to 20 years, a family can go from one mortgage to a small portfolio. It also has real risks, especially at today’s interest rates, so here is the honest version.
The Four Stages
Stage 1 (years 0 to 5): Buy and live. You buy a home you can comfortably afford, ideally with a low down payment program, and you stay long enough to build equity through principal paydown and, hopefully, appreciation.
Stage 2 (years 5 to 10): Move up, keep the first. You buy a larger primary residence and turn the first home into a rental, instead of selling it.
Stage 3 (years 10 to 15): Add or refine. Repeat the process, add a property with a different purpose, or use accumulated equity thoughtfully.
Stage 4 (years 15 to 20): Simplify and harvest. Pay down debt, sell the weakest holdings, and decide what to keep for retirement income or to pass on.
What One Home Alone Can Do
These numbers are an illustration, not a prediction. Assume a $400,000 home bought with 5 percent down, a $380,000 loan at 7 percent for 30 years, and appreciation of 3 percent per year. The payment is about $2,528 per month in principal and interest.
After 5 years, the home would be worth roughly $463,700 and the loan balance would be about $357,700, which is roughly $106,000 of equity. After 15 years, equity would be around $342,000. After 20 years, about $505,000.
That growth comes from two sources working quietly: paying down the loan and, if it happens, appreciation. One caution: Austin prices fell roughly 20 to 25 percent from their 2022 peak, so appreciation is an assumption, not a guarantee. The plan should still work if values are flat.
The Honest Part: Renting at Today’s Rates
Here’s where many online “wealth ladder” posts stay silent. Using the same home at the five-year mark, suppose it could rent for $2,700 a month. Principal and interest of $2,528, property taxes of about $696 a month, and insurance of around $290 add up to roughly $3,500 a month. That’s a shortfall of over $800 a month before vacancy and repairs.
If you refinance to 6 percent, the payment drops to about $2,145, which narrows the gap to roughly $430 a month but still doesn’t close it. Rental homes also don’t qualify for the homestead exemption, so their tax bills run higher than your own home’s.
Austin’s rental market adds context. Reported rent trends vary widely depending on the dataset, and apartment supply has grown enormously, with nearly 97,000 market-rate units added since 2020. Rents have been soft, though some measures show early signs of stabilization. So when you underwrite a rental, assume flat rent, not growth.
So Why Does the Strategy Still Work?
Because it’s a long-term plan, not a short-term income play. The loan payment is fixed, while rents tend to rise over time. The gap narrows year by year, and the principal paydown builds equity while you wait. A rental that loses a few hundred dollars a month in year five can approach break-even years later, but only if you can carry it comfortably in the meantime. That requires reserves, discipline, and the right property.
What Has to Be True
You can carry it. Keep cash reserves, ideally several months of full payments on each rental, plus a repair fund.
You buy for rentability. Choose homes in areas with steady employer and school demand, durable construction, and layouts that appeal to tenants. A home you love isn’t always a home that rents well.
You don’t over-leverage. Each additional property adds risk. Growth should never depend on everything going right.
You plan for taxes. Rental income is taxable, but depreciation, generally over 27.5 years, can offset some of it, and a 1031 exchange can defer gains when selling investment property. If you sell a former primary residence, the capital gains exclusion of $250,000 for a single filer and $500,000 for a married couple generally requires you to have lived there at least two of the last five years, which is why timing matters. Work with a CPA.
You use the right loan. Investment property loans generally require larger down payments and carry higher rates than owner-occupied loans. Buying your next primary residence with a low down payment and keeping the old home is usually more efficient than buying an investment property outright, but lenders have rules about occupancy, equity, and documented leases. Confirm them before you plan around it.
A Faster Path for Some: House Hacking
If you buy a two-to-four unit property and live in one unit, low down payment loans such as FHA can apply, and the rent from the other units offsets your payment. It’s less glamorous than a single-family home, but it often cash-flows better and teaches you to be a landlord with training wheels.
Protecting What You Build
Wealth built over 20 years can be undone in a day by a lawsuit, a disaster, or the loss of an income. Landlord insurance, adequate liability coverage, and a plan for how your family keeps the properties if something happens to a breadwinner are part of the strategy, not an afterthought. Mortgages don’t disappear when income does. That’s why I’ve expanded my work to include financial strategy alongside real estate, so families can acquire assets and protect them together.
Common Mistakes
Assuming rent will cover the mortgage at today’s rates. Skipping reserves. Buying a rental that’s hard to rent. Forgetting that rentals don’t get the homestead exemption. Losing the capital gains exclusion by waiting too long to sell. And scaling up too fast.
FAQ: Building Wealth With Real Estate
Q: Can I really turn my first home into a rental?
A: Often yes, but your lender’s rules on occupancy, equity, and documented leases matter, and the numbers need to work. See our guide to turning your first home into a rental.
Q: Will a rental pay for itself?
A: Not always, especially with low-down-payment loans at today’s rates. Plan to cover the gap until rents rise or you refinance.
Q: How many homes can a family realistically own in 20 years?
A: It depends on income, savings, and risk tolerance. Two or three well-chosen properties held long term can do more than many rushed purchases.
Q: Should I sell the first home or keep it?
A: It depends on its rentability, your reserves, and your goals. Run both scenarios with real numbers.
Q: What about taxes?
A: Rental income, depreciation, capital gains, and 1031 exchanges all apply. Work with a CPA, since the rules depend on your situation.
Q: What if prices don’t rise?
A: The plan should still work on principal paydown and rent growth, but returns will be lower. Never build a plan that requires appreciation.
Building wealth through real estate isn’t about buying more homes. It’s about buying the right ones, in the right order, with a plan to hold them. I help families map out their first purchase, their next step, and how to protect what they build.
If you’re ready to start your own ladder, let’s talk through the numbers together. Hablamos en inglés o en español.
(512) 217-3961
[email protected]
— Maria Aguirre
Mi Casa Agency | Keller Williams Lake Travis